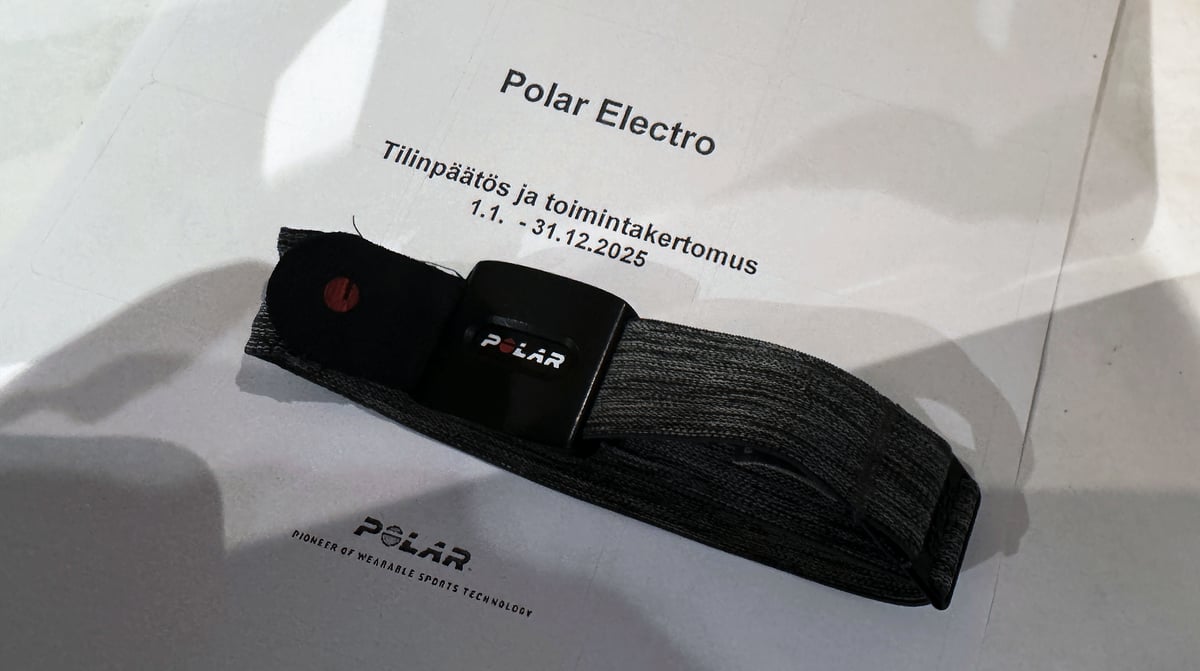
Polar’s financial position deteriorated in 2025. Turnover fell slightly, while its losses widened significantly.
- Turnover: €112.2m, down 2.75%
- Operating loss: €11.0m, up 42.8%
- Other operating costs: €26.0m, down 20.3%
- Materials and services costs: €47.3m, up 3.46%
- R&D spending: €20.2m, held flat at 17.9% of turnover
But the fuller picture is more complicated. According to its latest accounts, demand for Polar’s products remained fairly steady despite weak consumer confidence and cautious retailers. The company says Polar Loop’s launch was very successful, while registrations for Polar Flow continued to grow.
At the same time, Polar is cutting costs, restructuring its Finnish operations, and trying to earn more from the technology behind its products by licensing its sensors and Smart Coaching technology to other wearable brands.
The company is betting these changes will return it to profitability in 2026. The accounts show how much work remains.
The financial picture got worse.
Group turnover fell 2.75%, from €115.4 million in 2024 to €112.2 million in 2025.
The operating loss widened 42.8%, from €7.7 million to €11.0 million. The net loss grew 20%, from €12.4 million to €14.8 million.
The parent company, Polar Electro Oy, looks worse still on paper. It swung from a €983,000 profit in 2024 to a €5.2 million loss in 2025.
Its own trading loss barely moved, from €10.7 million to €12.5 million. Dividend income from its subsidiaries fell 31%, from €11.7 million to €8.1 million, meaning less cash moved up from Polar’s foreign operations to the Finnish parent that year.
But customers don’t seem to have gone away
Consumer confidence was weak in 2025, and retailers restocked cautiously. Even so, Polar says its products continued to sell well, which it takes as evidence that underlying demand held up.
Polar cites Polar Loop‘s September 2025 launch as one example, calling it very successful and tying it to interest from its growing business-to-business operations. Whoop has separately sued Polar, alleging that Loop copies its trade dress, the protected look of a product, and seeking to block US sales, a dispute the accounts do not mention.
Other signs of customer interest held up too. Regard for Polar’s products stayed high through 2025, the Net Promoter Score for its wrist devices stayed excellent, and new users kept registering devices with Polar Flow. Going into 2026, Polar expects that regard to continue, a large share of its customers to be new to the brand, and retailer inventories to stay very low.
What Polar is cutting
Average group headcount fell 3.6%, from 972 to 937, following negotiations with employees in Finland and temporary layoffs affecting both regular and senior staff.
Other operating expenses fell 20.3%, from €32.6 million to €26.0 million. Personnel costs barely changed, falling from €46.7 million to €46.2 million, while the cost of materials and services actually rose, from €45.7 million to €47.3 million.
Polar left research and development spending untouched.
| Metric | 2024 | 2025 | Change |
|---|---|---|---|
| Group turnover | €115.4m | €112.2m | -2.75% |
| Operating loss | €7.7m | €11.0m | +42.8% |
| Net loss | €12.4m | €14.8m | +20% |
| R&D spending | — | €20.2m | 17.9% of turnover |
| Average headcount | 972 | 937 | -3.6% |
| Group net worth | €29.4m | €13.4m | -54.3% |
| Inventory | €29.3m | €19.3m | -33.9% |
| Cash | €11.1m | €12.5m | +12.6% |
| Short-term borrowing | €14.5m | €16.7m | +15.2% |
| Operating cash flow | -€6.5m | +€0.77m | — |
Polar is trying to sell more than Polar watches and HRMs
Polar spent €20.2 million on R&D in 2025, 17.9% of group turnover, even though it cut other operating expenses substantially elsewhere. Polar says more of that investment now goes into technology that works across its product range, and into new ways to make money from it.
Powered by Polar means Polar’s technology reaches consumers who never buy a Polar-branded watch. It names licensing its Smart Coaching training features and sensor technology to third-party wearable brands and services an explicit 2026 priority.
Polar’s sensor technology already powers the Sennheiser Momentum Sport earbuds and the Motorola Moto Watch 2026, and a partnership with GreenTEG supplies core body temperature data to compatible Polar watches.
The accounts do not disclose what Powered by Polar or licensing revenue is actually worth, nor do they give meaningful geographic splits.
Polar is restructuring in Finland
In February 2026, Polar Electro Oy opened negotiations in Finland to reorganise the business and cut costs. Two subsidiaries, PE Austria and PE Norge, were wound up during 2025.
The balance sheet is harder to ignore
Cash rose from €11.1 million to €12.5 million during 2025, and operating cash flow improved from a €6.5 million outflow in 2024 to a positive €768,000. Most of that came from releasing cash tied up in inventory, which fell 33.9%, from €29.3 million to €19.3 million, rather than from improved profitability. Short-term bank borrowing rose from €14.5 million to €16.7 million.
Accumulated losses cut Polar’s net worth by more than half in a single year, from €29.4 million to €13.4 million. Polar still owns more than it owes, and cash on hand actually rose during the year. But short-term debts are also growing closer to what Polar can quickly turn into cash, and a net worth decline of this size in one year is worth watching if it continues.
KPMG’s audit report includes an emphasis of matter that highlights the going-concern discussion in the notes, where Polar says its financial situation remains challenging. The opinion itself remains unmodified, a milder signal than a qualified opinion, but still a genuine flag from the auditor. Polar’s optimism about 2026 comes with a real financial limit attached.
Where are the new products?
Polar entered 2026 with stronger signs from its customers and product pipeline, but with a net worth that has fallen by more than half and an auditor highlighting the group’s going-concern discussion.
The dearth of new products at the time of writing in September 2026 is striking. There are some leaks of some interesting things coming from them, but nothing Earth-shattering. Is the company really focusing on licensing and subscriptions, or perhaps skipping incremental launches to focus on a newer generation of tech, or something else? What do you think?
Polar Electro group financial statements 2025
Source: Polar Electro Oy consolidated financial statements for 1 January to 31 December 2025, filed with the Finnish Patent and Registration Office (PRH), business ID 0209911-2. Figures are in euros as reported. Costs are shown as negative figures. Materials and services is shown as a total.
Income statement, group
| Item | 2025 (EUR) | 2024 (EUR) |
|---|---|---|
| Turnover | 112,205,163 | 115,379,440 |
| Change in inventories of finished goods | -3,334,312 | 3,546,051 |
| Work performed for own use | 458,400 | 489,363 |
| Other operating income | 2,256,584 | 1,139,637 |
| Materials and services | -47,253,934 | -45,675,217 |
| Personnel expenses | -46,227,899 | -46,725,718 |
| Planned depreciation | -3,105,424 | -3,238,969 |
| Other operating expenses | -25,980,581 | -32,605,999 |
| Operating loss | -10,982,004 | -7,691,412 |
| Financial income from others | 840,010 | 899,474 |
| Interest and other financial expenses | -3,605,830 | -3,913,772 |
| Financial income and expenses, net | -2,765,820 | -3,014,298 |
| Loss before appropriations and taxes | -13,747,823 | -10,705,709 |
| Income taxes | -1,077,526 | -1,646,107 |
| Loss for the period | -14,825,349 | -12,351,817 |
Balance sheet, group: assets at 31 December
| Item | 2025 (EUR) | 2024 (EUR) |
|---|---|---|
| Intangible assets | 2,125,755 | 2,311,655 |
| Tangible assets | 9,198,551 | 10,637,960 |
| Investments | 8,715 | 8,715 |
| Total non-current assets | 11,333,021 | 12,958,329 |
| Inventories | 19,303,753 | 29,290,835 |
| Deferred tax assets | 864,622 | 793,647 |
| Short-term receivables | 17,558,184 | 20,029,431 |
| Cash and bank | 12,508,295 | 11,057,787 |
| Total current assets | 50,234,854 | 61,171,700 |
| Total assets | 61,567,875 | 74,130,029 |
Balance sheet, group: equity and liabilities at 31 December
| Item | 2025 (EUR) | 2024 (EUR) |
|---|---|---|
| Share capital | 436,000 | 436,000 |
| Share premium | 82,412 | 82,412 |
| Other reserves | 2,683,103 | 1,659,046 |
| Retained earnings | 25,056,196 | 39,549,545 |
| Loss for the period | -14,825,349 | -12,351,817 |
| Total equity (net worth) | 13,432,363 | 29,375,187 |
| Consolidation reserve | 0 | 4,720 |
| Pension provisions | 438,227 | 525,618 |
| Warranty provision | 2,283,233 | 1,710,961 |
| Total provisions | 2,721,460 | 2,236,579 |
| Other long-term debts | 286,143 | 323,877 |
| Capital loans | 4,250,000 | 4,250,000 |
| Loans from others | 16,700,000 | 14,500,000 |
| Trade payables | 8,138,433 | 8,753,755 |
| Accrued liabilities | 12,046,818 | 11,888,682 |
| Other short-term debts | 3,992,659 | 2,797,229 |
| Total short-term liabilities | 40,877,910 | 37,939,666 |
| Total equity and liabilities | 61,567,875 | 74,130,029 |
Cash flow statement, group
| Item | 2025 (EUR) | 2024 (EUR) |
|---|---|---|
| Operating loss | -10,982,004 | -7,691,412 |
| Adjustments to operating result | 2,468,051 | 5,905,162 |
| Change in inventories | 9,987,082 | -1,891,443 |
| Change in short-term non-interest-bearing receivables | 2,400,330 | 219,719 |
| Change in short-term non-interest-bearing debts | 738,244 | 1,616,866 |
| Financial income and expenses | -2,765,820 | -3,014,298 |
| Taxes paid | -1,077,526 | -1,646,107 |
| Cash flow from operating activities | 768,358 | -6,501,513 |
| Investments in other assets | 0 | -230,605 |
| Investments in tangible and intangible assets | -1,468,913 | -1,620,465 |
| Gains on disposal of tangible and intangible assets | -11,203 | 4,518 |
| Cash flow from investing activities | -1,480,116 | -1,846,552 |
| Cash flow before financing | -711,758 | -8,348,064 |
| Change in long-term loans | -37,734 | 0 |
| Change in short-term loans | 2,200,000 | 3,031,457 |
| Dividends paid | 0 | 0 |
| Capital loans drawn | 0 | 0 |
| Cash flow from financing activities | 2,162,266 | 3,031,457 |
| Change in cash | 1,450,508 | -5,316,607 |
| Cash at start of period | 11,057,787 | 16,374,394 |
| Cash at end of period | 12,508,295 | 11,057,787 |
Turnover by region
Polar’s accounts do not give a turnover split by region. The board report states that income from the Polar business was EUR 107.5 million in 2025, of which 90.5% came from international business.
Quick answers
How much money did Polar Electro lose in 2025?
Group net loss was 14.8 million euros in 2025, up from 12.4 million euros in 2024, on turnover of 112.2 million euros.
Did Polar's revenue actually fall in 2025?
Yes, but only modestly. Group turnover fell 2.75%, from 115.4 million euros to 112.2 million euros.
How much did Polar's operating loss widen in 2025?
Group operating loss widened 42.8%, from 7.7 million euros in 2024 to 11.0 million euros in 2025.
Why did Polar Electro Oy's own result swing to a 5.2 million euro loss?
Mostly because dividend income received from its foreign subsidiaries fell from 11.7 million euros to 8.1 million euros. The parent’s own trading loss barely moved, from 10.7 million euros to 12.5 million euros.
How many people does Polar Electro employ?
Average group headcount fell 3.6% in 2025, from 972 to 937, following negotiations with employees in Finland and temporary layoffs.
Did Polar cut its operating costs in 2025?
Yes. Other operating expenses fell 20.3%, from 32.6 million euros to 26.0 million euros. Personnel costs stayed nearly flat, while materials and services costs actually rose, from 45.7 million euros to 47.3 million euros.
Is Polar cutting research and development spending?
No. R&D spending held at 20.2 million euros, 17.9% of group turnover, even as other operating costs fell 20.3%.
What is Powered by Polar?
Polar plans to license its Smart Coaching training features and sensor technology to other wearable brands and services, an explicit 2026 priority in the accounts. It already covers products such as the Sennheiser Momentum Sport earbuds and the Motorola Moto Watch 2026.
Does Polar already license its technology to other companies?
Yes. Polar’s sensor technology powers the Sennheiser Momentum Sport earbuds and the Motorola Moto Watch 2026, and a partnership with GreenTEG supplies core body temperature data to compatible Polar watches.
How much does Powered by Polar earn the company?
The accounts do not say. Polar names licensing an explicit 2026 priority, but discloses no separate revenue figure for Powered by Polar or licensing income.
Is Polar Electro Oy financially at risk?
Polar’s group net worth fell 54%, from 29.4 million euros to 13.4 million euros, in a single year, and its auditor KPMG flagged the company’s going-concern discussion in its report. However, the audit opinion itself remains unmodified.
Is Polar in financial difficulty?
The accounts show real pressure, not a crisis. Polar still owns more than it owes and cash on hand rose in 2025, but net worth fell by more than half in a single year and the auditor flagged a going-concern discussion, worth watching rather than a cause for alarm.
Did Polar's cash position improve in 2025?
Yes, cash on hand rose to 12.5 million euros from 11.1 million euros, but mainly because Polar released cash tied up in inventory, which fell 33.9%, and increased short-term bank borrowing.
Did Polar's operating cash flow improve in 2025?
Yes. Operating cash flow turned positive at 768,000 euros, up from negative 6.5 million euros the year before.
Did Polar increase its borrowing in 2025?
Yes. Short-term bank borrowing rose from 14.5 million euros to 16.7 million euros.
What did KPMG say in its audit of Polar's 2025 accounts?
KPMG’s audit report includes an emphasis of matter that draws attention to the going-concern discussion in the notes, where Polar says its financial situation remains challenging. The opinion itself remains unmodified.
Is an unmodified audit opinion with an emphasis of matter the same as a qualified opinion?
No. An unmodified opinion with a flagged emphasis of matter is milder than a qualified opinion, though it does draw attention to a specific risk in the notes.
When did Polar Loop launch?
Polar Loop launched in September 2025. Polar’s board calls the launch very successful and ties it to interest from its growing business-to-business operations.
Is Polar Loop involved in a legal dispute?
Yes. Whoop filed a lawsuit alleging Polar Loop copies its trade dress and seeking to block U.S. sales. The accounts do not mention the dispute.
Is Polar's Net Promoter Score still strong?
Polar says the Net Promoter Score for its wrist devices stayed at an excellent level throughout 2025, and that regard for its products stayed high all year.
Is Polar Flow still growing?
Yes. Polar says new users kept registering devices with Polar Flow, its companion app and platform, throughout 2025.
What does Polar expect from retailers in 2026?
Polar expects a large share of its 2026 customers to be new to the brand, and says inventory levels at third-party retailers are very low heading into the year.
When did Polar start its Finnish restructuring?
Polar Electro Oy opened negotiations in Finland in February 2026 to reorganise the business and cut costs.
Did Polar close any subsidiaries in 2025?
Yes. Polar wound up two subsidiaries, PE Austria and PE Norge, in 2025.
Will Polar pay a dividend for 2025?
No dividend is mentioned for 2025 in the material covered here.
Does Polar expect to return to profit in 2026?
The board says it expects a positive result in 2026, citing cost efficiency, low retailer inventory, and a large share of new-to-brand customers. However, the accounts include no guarantee of this.
Last Updated on 3 October 2026 by tfk the5krunner
Small things I always use
- Garmin 90-degree charging adapter: Charges your Garmin from any USB-C cable. Essential when travelling. I use one.
- Body Glide: The blue anti-chafe stick swimmers and runners carry. I use it.
- Speedo earplugs: Fewer ear infections and no cold-water dizziness. I use them.
- Dryrobe Advance: My winter changing robe for open-water swims. I use one. A cheaper option is the AONYIYI changing robe.
- Maurten: Race fuel that stays easy on the stomach. I use them.
- Beet It Sport nitrate shots: Beetroot shots I take in the days before a race. I use them.
- Garmin charging puck: The quickest way to top up before a session. I use one.
- Injinji: Toe socks that stop rubbing, so you run more. I use them.
- Ultimate toe protectors: Stop black toenails on long runs. They work. I use them.
- Compressport R2 v2 calf sleeves: My calf sleeves of choice. I use them.
- Cellucor C4: My pre-workout before hard sessions.
- TPU tubes: Schwalbe Aerothan, Tubolito and Pirelli SmarTube. Light, tiny spares. I use all three.
- G8 insoles: Adjustable insoles that are good. I use them.
- Cycplus Cube: A 97g electric pump that gets a road tyre rideable in two minutes. I carry one. 5% off with code THE5KRUNNER.
Watches and sensors
- Polar H10: My daily driver for waking HRV.
- Polar Verity Sense: My backup arm-worn HR sensor.
- Nomad bedside charger: Charges my iPhone and Apple Watch overnight. I use it, and many of their bands.
- Train.Red: The best muscle oxygen sensor I’ve used.
- Tymewear: Accurate heart rate and reliable ventilatory zones. I use it to pace endurance rides over an hour.
- Garmin Forerunner 970: A pro-grade triathlon watch. I use this.
- Apple Watch Ultra 4: My daily smartwatch. No phone needed on rides.
- Garmin Fenix 9 Pro: I’ve just bought one.
On the bike
- Continental GP5000 for everyday riding, and Aero 111 on the front for special occasions.
- Helmets: Specialized S-Works Evade 3 for road riding, and Rudy Project Wing for TT-style races. I use both.
- Ravemen FR300: A front light that mounts under your Garmin or Wahoo. I use one.
- Wahoo TRACKR Radar: I use it on one bike and Varia on the other. They perform the same.
- Garmin Varia RTL515: Radar that warns you of cars from behind. I use this model.
- Wahoo ELEMNT Roam 3: The bike computer that’s easy to use. I use mine on most rides.
- Favero Assioma Pro RS2: Accurate power pedals that swap easily between bikes. I use this model.
Home and indoor training
- NPE Runn: Makes my basic treadmill smart, sending more accurate speed and distance to my watch and Zwift. I use it.
- Google Wifi: Keeps Zwift connected in my pain cave. I use it.
- Apple TV 4K: Zwift on the big screen. I use two.
- Google Nest Doorbell (wired, 2nd gen): My video doorbell, running in both Google Home and Apple Home. I use it.
Health, recovery and sleep
- FreeStyle Libre 3 Plus: Shows how my blood sugar responds to diet.
- hDrop: Measures my sweat loss in summer and indoors.
- Fourth Frontier Zone: Checks my heart under load in hard sessions.
- Oura Ring 5: My partner’s recovery tracker of choice.
- Eight Sleep: A cooling mattress cover my partner and I use nightly.
Reader-Powered Content
This content is not sponsored. It’s mostly me behind the labour of love, which is this site, and I appreciate everyone who supports it.
Support the site: Follow (free, fewer ads) · Subscribe (paid, ad-free) · Buy Me A Coffee
Written by real people, with AI assistance. Fact-checked and verified for originality. See the Editorial Policy. FTC: Affiliate Disclosure — some links pay commission. As an Amazon Associate, I earn from qualifying purchases.
tfk is the founder and author of the5krunner, an independent endurance sports technology publication. With 20 years of hands-on testing of GPS watches and wearables, and competing in triathlons at an international age-group level, tfk provides in-depth expert analysis of fitness technology for serious athletes and endurance sport competitors. See the gear tfk uses. ID

Let’s see if (they can launch a new chest strap that) can help. I’m hoping they launch a truly disruptive model that allows users to determine VT-1 and VT-2 thresholds, features a multi-sensor hub to connect devices like power meters and treadmills, operates entirely standalone without a watch while providing full data — including running leg balance directly from the strap
(I edited you comment slightly, ty for the comment)
all that would be feasible for a new HRM. Suunto’s new one helps with the VT1/VT2 by bringing some of the filtering algos to the chest strap.
by multi sensor hub what do you mean? something that pairs to multiple other sensors and then outputs one stream containing all of them? (power meter/indoor trainer)
IDK what angle polar could take. They must surely want something that coudl lead to a step change in sales and whislt me and you might like caching, running dynamics and dfa a1, i’m not sure there are huge sales linked to those. Safer bet is 3xBLE+ANT (which they do aleady) and simply improve the battery life. hardly earth shattering
Many thanks for the improvements.
Regarding the ability to accurately determine VT1 and VT2, I genuinely believe that if Polar could communicate the value of this feature, it would be perceived as having access to a personal laboratory assessment to identify precise training zones and ensure athletes are always training at the right intensity. Most endurance athletes understand the importance of training in the correct physiological zones, but many do not have easy access to laboratory testing. If Polar could position this capability as a practical and affordable alternative, I am convinced it could help drive additional sales while also strengthening the value proposition of the ecosystem through more accurate and actionable metrics.
In particular, I think the addition of breathing rate and breathing pattern analysis, measured directly through the HRM, would be a game changer. What Tymewear has achieved in this area is, in my opinion, outstanding.
Looking slightly further ahead, I believe there is an opportunity to create an integrated solution where Polar combines heart rate, respiration and threshold detection into a single seamless experience. This would be a unique differentiator in the market and would further reinforce Polar’s reputation as the brand most focused on physiological metrics and training science.
As for the Hub concept, what I envision is something slightly different. Imagine an HRM sensor with an integrated GPS chip capable of recording all key training metrics independently. In that scenario, there would be no need for a watch or screen at all. You would simply wear the chest strap, start recording, train, and forget about the device entirely. Afterwards, everything would sync seamlessly to the Polar ecosystem.
For athletes who prefer to train without anything on their wrist, this could be an incredibly appealing solution. It would also appeal to runners, triathletes and cyclists looking for the lightest and simplest setup possible while still capturing all the performance and physiological data that matter. Combined with respiratory monitoring and advanced threshold detection, such a device could represent a completely new category within the Polar ecosystem.
yes. whoop on the chest!!! good idea
breathing volume requires a strain guage, which is on the tymewear strap.
breaths per minute can be measured from hrv but that is not the same thing.
this would require a potentially delicate new strap version and all the issues that might come with that.
An increase in Net Loss from 14.4m to 14.8m isn’t +20% as the table says. It’s +2.78%..
The actual calculation: (€14.8m − €12.4m) / €12.4m = 19.35%, which the article rounds to “20%.” That’s correct as published
Lackluster products (bar the HR straps) since the mighty V800 in 2014 (or 2018 with its successor).
Am I the only one who feels that with a bit more love and care, customer demand research, fine tuning before release paired with more reasonable pricing, Polar could of done better?
interestingly i’m doign a high level brand comaprison and polar comes out very highly (just the brand not the products)
Good catch. I’d been sporadically rememebering to check the financials, but they hadn’t been posted yet at my last check.
But indeed, this seems to jibe well with the near-daily “40% off Sale” e-mails I get from Polar.
One of the challenges I think Polar has with NPS, is that NPS is heavily focused on keeping existing customers happy. And in most cases, that drives new customers, in Polar’s case, I think it’s a bit different. Polar’s remaining customer base is *heavily* loyal to it, going back many years (something I see every time I publish a review). And based on the wording of those long-time customers, I can see they don’t often have as much experiance with competitors (e.g. COROS, Amazfit Suunto, Garmin, Apple, Samsung, etc…). And in turn, often have outdated perspectives of the competitors.
Therefor, when it comes to that base of users recommending Polar devices to others, it hasn’t carried as much weight because many times those viewpoints get quickly dismissed with the current reality of their competitors.
I don’t know at this juncture how Polar gets out of this pickle (I genuinely don’t), especially as we sit here over a year after the Polar Loop release without any meaningful change in features/gaps/etc…
Looking at Polar’s financials, their R&D spend is roughly 3x higher than Suunto’s, yet I’m struggling to see what that investment has actually produced over the last five years.
The Vantage V3 range type of watches was supposed to be the big leap, Amoled display, new optical HR sensor (which isn’t the most accurate), dual‑band GNSS (which isn’t the most accurate), and maps (which everyone else already had). Meanwhile Suunto, with a much smaller R&D budget, has delivered far more meaningful innovation in my opinion, from the Suunto Vertical’s excellent GNSS performance to their mapping implementation and regular software ecosystem improvements.
@the5krunner @DCRainmaker, I’d appreciate your take on this. You both follow these companies far more closely than I do.
Is Polar’s significantly larger R&D budget simply not translating into product‑level innovation, or is there something else happening? E.g. different accounting method?
IDK that detail.
There could be grants for R&D like in the UK which then makes companies artificially inflate r&d spend to qualify
or more likely Suunto is buying in the tech rather than inventing it, reducing internal r&d spens
Polar is also meant to be launching a refreshed app (6 months ago!!) there will be labour costs there
just speculating